
 (888) 999-1405
Debt Consolidation: Everything you need to know
Quick Answer: Debt consolidation is a strategy that uses one new loan to pay off several existing debts, leaving you with one monthly payment, one interest rate and one payoff date. It works best for people with several high-interest balances, such as credit cards, who can get a lower APR and stop adding new debt. Always compare the total cost, including origination fees of 1% to 6%, before you consolidate.
Why Should You Learn About Debt Consolidation?
The year 2020 was harsh on almost everyone. If you were not in the top 1%, chances are that it was harsh on you as well. Estimates at the time said that 49% or more people in the U.S. expected to live paycheck to paycheck that year. Moreover, an average American household carried around $8,400 in credit card debt.
These are alarming figures and if you’re struggling with your debts, then we have something for you. There are a lot of strategies you can use to pay off your debt. One such strategy is debt consolidation. But, we’d like you to make an informed decision. For that reason, we’re going to help you with all you need to know about Debt Consolidation in this article.
You’ll learn about debt consolidation, how you can use debt consolidation effectively, things to take care of, pros and cons of debt consolidation, and whether debt consolidation is right for you.
Let’s begin with understanding debt consolidation.
Who Is This Guide For?
This guide is for people who carry several credit card balances, medical bills or personal loans and find it hard to keep track of many payments.
Use it when you have a steady income and a plan to avoid new debt, and want to know whether consolidation will lower your cost or monthly payment.
What is Debt Consolidation?
Debt Consolidation is used to combine and replace your existing debt to reduce its burden using an unsecured personal loan. So, if you take out a debt consolidation loan, you use the money borrowed to pay off your other debts. You can use it to pay off debts like credit card balances, medical bills, and more.
With a debt consolidation loan, you’ll have one monthly payment amount and one monthly due date only. This helps you avoid the hassle of having to pay several different lenders.
Debt consolidation loans are mostly used to pay off and combine credit cards, personal loans, or other debt.
Debt consolidation loans help you simplify your monthly payments. Not just that, they also help you avoid high credit card interest rates and save money. Streamlining and consolidating your debts can help you steer clear of the monthly payments you can’t afford. All such difficult monthly payments will be replaced by one single manageable payment.
You’ll only have one new loan with a new interest rate, new monthly payment, and new payoff date. Take care to choose a debt consolidation loan with the right terms that take you closer to your debt goals.
Who is Debt Consolidation for?
Debt consolidation is not for everyone. If you have a reasonable amount of debt and have a plan in place to avoid future debt, then it might be right for you.
In such a situation, debt consolidation might help you lower your monthly interest rate. Or it can even adjust the terms of the loan to a lower monthly payment. So, if used correctly, debt consolidation can allow you to save money while paying off your balances faster than before.
Advantages of Debt Consolidation
Fixed Payment with Lower Interest Rate
The interest rate on your debt consolidation loan might be lower than the rate you’re paying on your existing balances. Over time, this can save you a significant amount of money.
Moreover, if you choose a loan with a fixed interest rate, then your monthly payment will remain the same as throughout the repayment period. This can help make budgeting easier for you.
Fixed End Date
With a loan, there’s always a set amount of time during which you’ll be paying back your debt. The same is not true with a credit card. With a credit card, you don’t have a set date when you’ll be finished paying off your debt. You can continue to use your card while paying off the debt. This can increase your total balance and the amount of interest you’ll pay.
No Collateral
In debt consolidation, you have the option to go for an unsecured debt consolidation loan. Such a loan will not use your home or vehicle as collateral. So, your personal property and assets will be safe and secure.
Disadvantages of Debt Consolidation
Interest Rates, Fees, and Costs
Make sure that the interest rate on a debt consolidation loan is lower than the rate on your existing debt. Lenders may charge origination fees, application fees, prepayment fees, late fees and other fees. Before you sign anything, ask the lender to tell you if there are any fees associated with the loan. Also, enquire about the total amount you’ll pay in fees.
Higher Payments
In a debt consolidation loan, you set a fixed amount of time to pay off your loan. This can increase your monthly payment more than the amount you were paying on your debts before consolidation. Before you decide to consolidate your debt, ensure that the payment on your loan won’t strain your budget.
How can you use a Debt Consolidation loan to improve your financial situation?
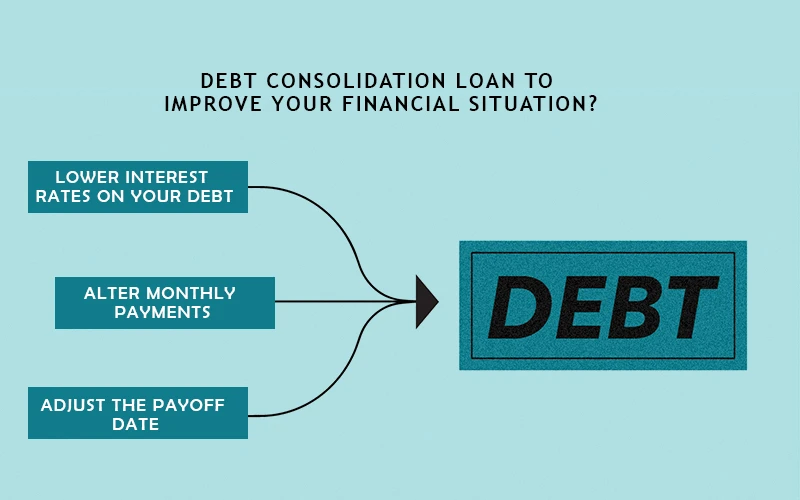
Let’s take a look at a few ways in which a debt consolidation loan can help improve your financial situation.
Lower interest rates on your debt
Debt consolidation is so enticing because it gives you a chance to pay less interest. However, you’ll need a good credit to consolidate debt to a lower interest rate.
If you have a good credit rating, getting a lower interest rate on a debt consolidation loan might be simple. But, don’t get disheartened if you have average or fair credit. A borrower with average credit might also be able to save by consolidating high-interest debt to a lower amount.
Alter Monthly Payments
Debt consolidation also gives you a chance to modify or change your monthly payments. It makes your life simpler by replacing multiple monthly payments with a single, easy-to-track payment.
You can also lower your monthly payments by getting a lower interest rate or choosing a longer repayment plan. If debt repayment is straining your budget, consolidating it can make enough room for you to breathe and sustain.
Adjust the Payoff Date
With debt consolidation, you are also given the opportunity to adjust and alter your payoff date.
Your loan term and payoff date affect the total interest you pay over the life of the loan. A shorter term implies higher monthly payments but it’ll help you avoid years of interest charges.
Do your math to see if it’s worth extending the payoff date on your debt consolidation loan. Having this option makes debt consolidation all the more beneficial and flexible.
What Should You Take Care of in Debt Consolidation?
Before you decide to go for debt consolidation, make sure that you check the following details:
Take Origination and other fees into account
A lot of debt consolidation loans also carry origination fees in addition to interest charges. These fees can range anywhere from 1% to 6% of the total loan amount. Such fess can add to your total loan costs.
Generally, origination fees are taken out of the loan funds before the lender disburses them to you.
Not all lenders charge this fee, so you might want to apply with those that don’t charge it. You should also compare APRs on debt consolidation loan offers. APRs will reflect the total loan costs, including the interest rate and origination fee.
Don’t borrow after Consolidating your Debt
You must have a post-debt consolidation plan in place if you opt for debt consolidation. Consolidation of debts must be followed by a responsible plan of action to avoid taking on additional debt.
Once you have consolidated your debt, you might free up available lines of credit. Make sure that you have a strategy in place to avoid charging new purchases to your credit cards. If not, you might max them out and end up in twice as much debt.
Is Debt Consolidation right for you?
You must do your research and due diligence before deciding to go for debt consolidation. It’s probable that after doing your research you realize that it’s not right for you.
Maybe you are already paying low interest rates so debt consolidation won’t help you much. Or, maybe you have a bad credit history which is making it difficult for you to opt for debt consolidation.
If it’s not for you, it’s not for you but that does not mean that you have no options left. You can make a strategic plan to pay off your debts, change your financial habits a bit, and pay extra on your debts whenever possible.
Let’s assume that you’re struggling with your current payments. Or maybe you are at risk of defaulting and still have several years left on your loans. In such a case, debt consolidation might be a great option for you.
But if you’re managing to make the payments and only have a couple of years left until your payoff date, you might want to consider other options instead.
At the end, you have to make a choice. Whether it is worth going for debt consolidation for your specific situation or not. Give this decision a deep thought and think about it from all perspectives before reaching a decision.
What Do the Numbers Say About Debt Consolidation?
The Federal Reserve’s consumer credit data for August 2026 shows an average credit card rate of 22.36% on accounts that pay interest. The average 24-month personal loan rate is 11.90% (Federal Reserve, Consumer Credit G.19 release).
The Consumer Financial Protection Bureau advises comparing the total cost of a consolidation loan, including fees, with what you pay now before you consolidate (Consumer Financial Protection Bureau, consolidating credit card debt).
| Option ($8,400 over 36 months) | Rate | Monthly Payment | Total Interest and Fees |
|---|---|---|---|
| Keep paying the credit cards | 22.36% | $322.37 | $3,205.19 |
| Consolidation loan, no fee | 11.90% | $278.60 | $1,629.57 |
| Consolidation loan with 5% origination fee | 11.90% | $293.26 | $2,157.44 |
Case Study: We Ran the Numbers on $8,400 of Credit Card Debt
In our experience at GConnectPro, the borrowers who benefit most from consolidation are the ones who stop adding new spending right after they consolidate.
We used the $8,400 average household credit card balance from the start of this article. Paid off over 36 months at 22.36%, it costs about $3,205.19 in interest. A consolidation loan at 11.90% cuts that to about $1,629.57, a saving of about $1,575.62.
With a 5% origination fee, the saving drops to about $1,047.75. That is why you must compare APRs and fees, not just the interest rate.
Key Takeaways
Debt consolidation saves money only when the new APR, including origination fees of 1% to 6%, is lower than what you pay now, and when you stop adding new debt after you consolidate.
How Can GConnectPro Help You?
You should consider debt relief if the burden of debt is too great for you to manage on your own. Debt relief can help you get your finances under control if you’re struggling to keep up with multiple types of debt.
GConnectPro can provide the required support to people overburdened by debt. On your behalf, we’ll negotiate with creditors to reduce monthly payments, rates and the amount you owe. We can also help you restructure your debts into a single monthly payment plan. Moreover, you can approach GConnectPro if you need counseling to help you create a budget that works. We’re here to help you, even in the most difficult of times.
Got any questions? Let us know in the comments below or apply here for free online consultation.
Frequently Asked Questions
Does debt consolidation hurt your credit score?
Applying for a new loan can cause a small, temporary dip because of the hard credit check. Making on-time payments on the new loan can help your credit over time.
What debts can I consolidate?
Debt consolidation loans are mostly used to pay off credit card balances, personal loans, medical bills and other unsecured debt.
Is debt consolidation the same as debt relief?
No. Debt consolidation uses a new loan to pay your debts in full. Debt relief involves negotiating with creditors to reduce your payments, rates or the amount you owe.
How much can I save with debt consolidation?
It depends on the rate gap and fees. In our example, consolidating $8,400 of credit card debt saved about $1,576 in interest without a fee and about $1,048 with a 5% fee.

Write a reply or comment
You must be logged in to post a comment.