
 (888) 999-1405
Merchant Cash Advance, How To Get Your Business Approved If You Have Been Denied Once?
Quick Answer: If your merchant cash advance application was denied, ask the funder why it was rejected. Then fix those issues before you reapply. Check your application twice for missing details or wrong figures. Wait to reapply if your card sales are low, or apply to a different funder with more flexible terms. Also compare other options, such as small business loans, business credit cards or lines of credit.
What Should You Do After a Merchant Cash Advance Denial?
On the off chance that your business wasn’t affirmed for a trader/business loan, don’t stress. You are not the only person who has come across this business fund freezing moment. Numerous business loan funding agents/institutions investigate applications intently.
They regularly consider your Mastercard deals and credit card sales, generally speaking, month-to-month deals sum, and other monetary variables. On the off chance that you don’t meet their necessities, you will not be affirmed for a vendor loan. You may know it better as the Merchant Cash Advance.
Here is the most important point of all. In any case, don’t allow a mere letter of disapproval of MCA to get your confidence or spirits down! Nobody likes getting dismissed. Notwithstanding, there are steps you can take to build your risks of getting endorsed for a future loan.
In this post, we’ll clarify how you can improve the probability of getting your next vendor loan application endorsed.
A Merchant Cash Advance. (MCA) isn’t an advance or specifically classified as a loan. Rather, it is a loan depending on the credit card deals stored in a business merchant account. An entrepreneur can apply for an MCA and have reserves stored into a business financial records lightning fast. In some cases, it is as fast as 24 hours after endorsement or even less.
MCA providers assess the individual hazard, financial risk, and weight credit measures uniquely. This is in contrast to a private financier or banker. These finance providers go through your everyday and monthly transactions very carefully. They check and confirm if the borrower can repay the blended money (loan) in a fixed decided timeline. That timeline is fixed and can attract punitive measures if not paid on time.
The Visa and credit receipts are evaluated in detail. This helps decide whether a business, its owner, and the security provider can take care of the development in a convenient way. Accordingly, rates on an MCA can be a lot higher than other financing alternatives. So, it’s basic you comprehend the terms you’re being offered. Then you can settle on an educated choice about whether an MCA bodes well to address your issues and requirements.
Inside the setting of an MCA, the expression “holdback” is likely the most unnatural. The holdback sum is the level of day-by-day Mastercard deals applied to your development. The holdback rate (somewhere close to 10 percent and 20 percent is ordinary) is generally fixed. It stays that way until the development is reimbursed.
Reimbursement depends on a level of the day-by-day balance in the dealer account. So, the more charge card exchanges a business does, the quicker they’re ready to reimburse the development. Also, should exchanges be lower on some random day than anticipated, the draw from the vendor record will be less. All in all, the restitution is normally comparative with the approaching Visa receipts and credit details.
There’s a contrast between the loan fee an entrepreneur is charged for the development and the holdback sum. Most MCA suppliers charge what’s known as a “factor rate”. Dissimilar to a customary term credit, the rate isn’t amortized throughout the development. A run-of-the-mill factor rate for an MCA could go among twofold and triple digits relying on the supplier.
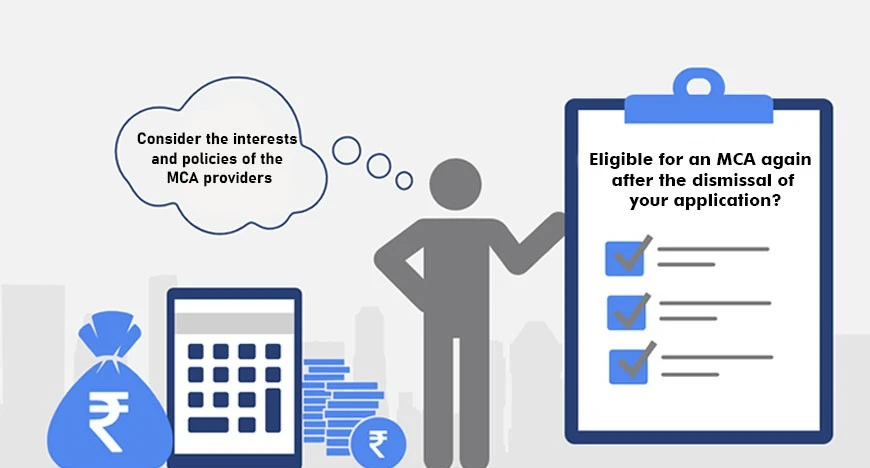
How to become eligible for an MCA again after the dismissal of your application?
Speedy Tips to read:
- Be respectful, proficient, and do not think about dismissal Personally.
- Request particulars, including how you could deal with getting your application cleared later on.
- Consider the interests and policies of the MCA providers. After all, they are the sole pretext who will fund your small business and make a move. This is true regardless of whether you plan on applying to an alternate funder.
- There is an off chance that the sales and deals on your credit card are low for the time being. If so, it probably is not a good idea to apply immediately. Instead, have some patience and apply when your credit scores are back on the track.
- Apply to an alternate funder. They may have more indulgent capabilities. This makes it simpler for you to get your application affirmed with all the green signals.
- Gain from an earlier time. What made your application beforehand be dismissed? How might you address it with the goal that you can get endorsed sometime later?
1. First things first, ask the Funder “why your application was Rejected?
Is it accurate to say that you are uncertain of why your application was dismissed? It is not bad but a good idea to directly go to the source i.e. your loan supplier/approver that you applied through.
In the market, there are numerous dealers and loan organizations that will reveal to you why your application was dismissed. When you understand what their interests were, you might have the option to address them while applying later on.
While reaching the trader loan supplier or your funding approver, keep patience and be transparent. It might be consuming and affect your psyche if you continue to think about your application dismissal. Be that as it may, loan suppliers should run monetarily capable tasks. There are sure dangers they attempt to stay away from. This of course is an important part of their job, to keep the fraudulent loan seekers away. That is why you should be as transparent and truthful.
When you comprehend their perspective, you might have the option to reapply. In any event, you can remember their interests while applying with different suppliers.
2. Be smart and check your application twice before making a reapplication
We comprehend that as an entrepreneur, you’re generally in a hurry. You like to get your things fixed and get done ASAP. Because of this, you may be bound to simplify blotches on your application. This is basically because you’re shuffling such countless undertakings without a moment’s delay.
In any case, it’s imperative to focus on subtleties while finishing your application. Neglecting to incorporate data or giving off base figures could make you get precluded.
Sometimes, your funding official may circle back to you to fix the specific issues. He has found them out in your previous as well as the newly applied re-application. Many fund suppliers in the market will utilize this as motivation to dismiss your application. But then again, you got to clear things out on your end. Do this by keeping the transparency as much as possible in disclosing your details. Then come out as a legit fund seeker. You see, it’s your business and you treat your business as your blood child.
You take an extra mile to provide the best to your child, don’t you? Before presenting your application, require a couple of moments to carefully audit it. Also, have either your accomplice or a representative who has and keeps your trust. They should present your interest as his interest. By re-perusing and remedying your answers, you could save your business from another dismissal.
3. Apply to Another Merchant Cash Advance Funder
Smart business owners like yourself must understand that one rejection is not the end of the business. That being said, take your rejection as a learning experience. Then come out as a more solid applicant by keeping all the pointers in mind. These were the pretext of your application dismissal.
Make good use of your rejected application by getting it fully analyzed by a champion auditor in the market. Once you find the issues, you can further ask the auditor to fix the issues in your application. That’s how you roll and make sure that your new application doesn’t get rejected again. Instead, it should deliver the result that you were expecting, i.e. getting the approval of the funds for your business. Dismissal isn’t the apocalypse.
Truth be told, you could see it as a positive learning experience. By realizing why you were dismissed and how you can improve your application, you’ll increment your odds of future achievement. On the off chance that you’ve been dismissed by one funder, that doesn’t imply that you should call it quits.
All things being equal, apply to an alternate loan supplier. As you gain from your errors and more about the endorsement interaction, you’ll have the option to improve your application. This will build your odds of accomplishment.
4. Check out for more available option for your new application
A loan can be an incredible method to rapidly get the money infusion your business needs. Notwithstanding, in case you’re experiencing difficulty getting endorsed for a loan, think about elective types of financing.
Private company advances, charge cards, credit extensions, and different sorts of monetary subsidizing are accessible. It’s pivotal that you research these financing items preceding applying.
At times, these different types of financing will be more qualified for your organization. For instance, suppose your clients don’t utilize Mastercards oftentimes out of the blue. In any case, your business receipts show solid execution.
For this situation, an independent company credit might be more proper. Or on the other hand, you may like having a business Mastercard available for buys. You can rapidly pay those off inside the month. In any case, it’s critical to decide the financing choice that will best suit your business requirements.
Keep all these pointers in mind before applying for the new MCA fund-seeking application. Then you won’t see the rejection but the approval coming your way.
Case Study: How I Rebuilt a Denied Merchant Cash Advance Request
In our experience, many denials come from asking for more than the card sales can repay. Sizing the request to monthly sales is often the simplest fix.
I tested this on one sample business with $30,000 in monthly card sales and a 15% holdback. I used an illustrative 1.3 factor rate and compared a $60,000 request with a $30,000 one. Here is what we found:
- Daily card sales of about $1,000 meant a daily holdback of about $150.
- The $60,000 request meant a $78,000 payback, or about 520 days of holdbacks.
- The $30,000 request meant a $39,000 payback, or about 260 days of holdbacks.
The result: right-sizing the request cut the estimated payback period from about 520 days to 260 days.
Frequently Asked Questions
What should I do first after an MCA denial?
Ask the funder why your application was rejected. Knowing their concerns helps you address them before you reapply.
What is a holdback in a merchant cash advance?
The holdback is the share of daily card sales applied to repaying the advance. A range of 10% to 20% is typical.
Should I apply to a different MCA provider?
Yes, if needed. Another funder may have more flexible requirements, which can make approval easier.
Are there alternatives to a merchant cash advance?
Yes. Small business loans, business credit cards and lines of credit may suit your business better.

Write a reply or comment
You must be logged in to post a comment.