 (888) 999-1405
ERC Qualification Requirements: Not Just On The Basis Of Revenue
Quick Answer: ERC eligibility did not depend on revenue alone. A full or partial shutdown under a COVID-19 government order could qualify a business. No big revenue drop was needed. For 2021, a decline in gross receipts of 20% or more versus the same 2019 quarter also qualified. Non-profits, including churches, could qualify too. Employee count mattered, with thresholds of 100 employees for 2020 and 500 for 2021. Employers also needed documentation to support every claim.
Is Revenue Decline the Only Way to Qualify for the ERC?
ERC (Employee Retention Credit) is a tax credit that was introduced by the U.S. government as a measure to help businesses retain their employees during the COVID-19 pandemic. The credit is designed to help businesses keep employees on their payroll. This applies even if their operations have been disrupted due to the pandemic. The credit has been amended several times since its initial enactment as part of the CARES Act in March 2020.
One of the most significant changes to the ERC has been the expanded eligibility criteria beyond just revenue decline. The ERC can provide a significant financial benefit to businesses that qualify. However, many business owners are unsure if they meet the eligibility requirements.
With this in mind, in this blog, we’ll take a closer look at the ERC qualification requirements beyond revenue decline. We’ll also explain why revenue is not the only factor that matters.
The Basics of ERC Qualification Requirements
To qualify for the ERC, businesses must meet certain eligibility requirements, which can be divided into two categories:
Eligibility requirements for 2020: For 2020, businesses must have experienced a full or partial suspension of operations. This had to be due to government orders related to COVID-19. Otherwise, they needed a significant decline in gross receipts.
Eligibility requirements for 2021: For 2021, businesses must have experienced a full or partial suspension of operations. This had to be due to government orders related to COVID-19. Otherwise, they needed a decline in gross receipts of 20% or more compared to the same quarter in 2019.
DID YOU KNOW?
The decline in gross revenue is an important factor in determining eligibility for the ERC. However, it is not the only factor. Businesses that do not meet the gross receipts threshold may still be eligible if they meet other requirements.
Some employers have experienced a government-mandated shutdown, supply chain disruptions, or a lack of available employees. They may still be eligible for the credit. This holds even if they have not experienced a significant decline in gross receipts.
Non-profits are also eligible for the credit, and there are some exceptions to the employee threshold. Employers must meet all the eligibility criteria and provide documentation to support their claim for the ERC.
For example– Some businesses were not in operation in 2019. They can compare their 2021 gross receipts to the average quarterly gross receipts in 2020. Additionally, businesses that experienced a full or partial suspension of operations due to COVID-19 can qualify for the ERC. This holds regardless of their gross receipts.
How The Decline In Gross Receipts Is Calculated And What Qualifies As A Significant Decline
It is important to note that the ERC is available to eligible employers. Some have experienced a full or partial suspension of operations due to COVID-19. Others have seen a significant decline in gross receipts during 2020 or the first three quarters of 2021.
The calculation of credit is performed on the basis of qualified wages offered to employees during the qualified period, i.e. $10,000 per employee.
The employer who qualifies for the ERC has been credited with a maximum of 50%. This applies to the first $10,000 in qualified wages. That is up to $5,000 per employee.
However, what many employers may not realize is that they may still be eligible for the ERC. This holds even if they have not experienced a significant decline in gross receipts. This is because the eligibility criteria have been expanded to include other factors. These factors may have impacted the business due to COVID-19.
For example – An employer may have experienced a government-mandated shutdown. It may also have been unable to operate due to supply chain disruptions or a lack of available employees. In either case, it may still be eligible for the ERC.
Employers Who are Eligible For The ERC
It is worth noting that the ERC is not only limited to for-profit businesses only. Some other Non-Profit Organizations (NPO) such as religious organizations, and churches are also eligible for the ERTC benefits.
The eligibility criteria for non-profits are slightly different, but they still include factors beyond revenue decline. Non-profits can qualify for the ERC if they have experienced a full or partial suspension of operations due to COVID-19. They also qualify with a significant decline in gross receipts during 2020 or the first three quarters of 2021.
The calculation of credit is done on the basis of qualified wages paid to the employees during the eligible period. This is up to $10,000 per employee.
For the non-profit employer, the maximum credit calculation is 50% of the first 10,000 in qualified wages. This is up to $5000 per employee.
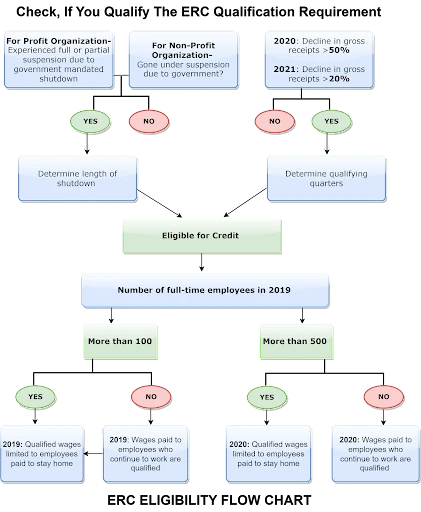
Let’s understand the above via ERC Eligibility Flow Chart –
Looking Beyond Revenue: Other Qualification Requirements For ERC
Another important factor to consider is the size of the business and the number of employees the business have. In 2020, businesses with 100 or fewer employees could claim the ERC for all employees. This applied regardless of whether they were working or not. For 2021, the threshold was increased to 500 or fewer employees.
Employers with 500 or fewer employees are generally eligible for the credit, but there are some exceptions. For example, an employer may have more than 500 employees. If it has experienced a government-mandated shutdown, it may still be eligible for the ERC.
Also note that businesses cannot claim both the ERC and the PPP (Paycheck Protection Program) for the same wages. Suppose a business received a PPP loan in 2020. Then it cannot claim the ERC for the same wages paid with PPP funds.
However, businesses that received a PPP loan in 2021 can still claim the ERC for eligible wages. For this, it is compulsory that employers should also aid legit documentation to support their claim for the ERC.
As Has Been Demonstrated
The decline in gross receipts is an important factor in determining eligibility for the ERC. However, it is not the only factor. Businesses that experienced a full or partial suspension of operations due to COVID-19 can qualify for the ERC. This holds regardless of their gross receipts. Additionally, businesses cannot claim both the ERC and the PPP for the same wages. To qualify for the ERC, businesses must also maintain documentation to support their eligibility.
The ERC can provide a significant financial benefit to businesses that qualify, but navigating the eligibility requirements can be complex. Business owners should work with their tax advisors to determine whether they meet the qualification requirements. They should also ensure that they are properly documenting their eligibility for the ERC.
You may believe your business is eligible for the ERC. If so, it is important to consult with a professional company like Gconnectpro.com. This helps ensure you meet all the requirements and maximize your credit. By taking advantage of this tax credit, businesses can help to mitigate the financial impact of the COVID-19 pandemic. They can also retain their valuable employees.
Case Study: How I Tested ERC Eligibility Beyond the Revenue Rule
In our experience, many owners stop at the revenue test and never check the government order test. Running both tests side by side gives a clearer answer.
I tested this on one sample business with $200,000 in gross receipts in a 2019 quarter. I compared it with 2 possible 2021 results. Here is what we found:
- The 20% decline line for that quarter is $160,000, since 80% of $200,000 equals $160,000.
- At $150,000 in 2021 receipts, the business was at 75% of 2019, so it passed the revenue test.
- At $170,000 in 2021 receipts, the business was at 85% of 2019, so it failed the revenue test.
- In the $170,000 case, only a full or partial shutdown from a government order could still qualify it.
The result: when receipts fell from $200,000 to $150,000, the 25% decline cleared the 20% threshold on revenue alone.
Frequently Asked Questions
Can a business qualify for the ERC without a revenue decline?
Yes. A full or partial shutdown from a COVID-19 government order could qualify a business. Gross receipts did not matter in that case.
What gross receipts decline qualified for the ERC in 2021?
For 2021, a decline of 20% or more compared with the same quarter in 2019 qualified. Businesses not operating in 2019 could compare to their 2020 average quarterly receipts.
Can non-profits claim the ERC?
Yes. Non-profits, including religious organizations and churches, could qualify. They used the same suspension of operations or gross receipts tests.
Can I claim the ERC and PPP for the same wages?
No. A business cannot claim the ERC for the same wages paid with PPP funds. Wages not covered by PPP forgiveness may still count.

Write a reply or comment
You must be logged in to post a comment.